Could AI Change Everything—and Investors Still Lose?

Preston Werth • October 27, 2026

Share this article

Most investors have followed the extraordinary share-price gains of Nvidia and other beneficiaries of the AI boom, so enthusiasm for the industry is understandable. But will shareholder returns from here match the excitement, and how much of the anticipated growth is already reflected in today’s valuations?


The technology is transformational. Demand for compute is real and growing. And the productivity improvements are tangible. Nevertheless, investing in a theme hasn’t always been a sound strategy. Gus and I are wired cautiously, which tends to make us skeptics and contrarians (sometimes to my wife’s dismay).


The capital committed to AI infrastructure has been eye-popping: Goldman Sachs estimates that global AI-related investment will exceed $1 trillion in 2026 alone.1 Suppliers to this buildout have benefited accordingly. But how long can this level of spending continue?


History suggests skepticism isn’t unfounded: past buildouts of transformational technologies have often ended in overinvestment. After the internet boom, an estimated 95% of installed fiber sat unused in 2001,2 and excess capacity persisted for years. In the 1880s, U.S. railroad mileage increased about 75%,3 and by 1894 roughly a quarter of it was in receivership.4 In 1909, there were 272 U.S. automobile manufacturers, but by 1941 only nine remained.5


Railroads transformed commerce, automobiles transportation, and the internet communication, while fracking revolutionized American energy production. Yet in each case, considerable economic value accrued to consumers or users of the technology, but that value did not always translate into attractive returns for the investors footing the bill.6 The excess fiber laid during the internet buildout, for example, helped drive wholesale bandwidth prices down more than 95% between 1998 and 2007,7 providing cheap “plumbing” that allowed companies like YouTube and Netflix to flourish over the following decade.


Consider Cisco, a leading supplier of internet-related hardware in the late 1990s. Following three years of roughly 44% annualized revenue growth, Cisco briefly became the world’s most valuable publicly traded company in March 2000, with a market capitalization of $555 billion, trading at more than 200 times earnings. Investors who purchased at its $80.06 high watched the stock decline nearly 90% by October 2002. Its share price didn’t regain that high until December 2025—nearly 26 years later.8 The internet proved as transformative as investors anticipated, and Cisco remained a strong business. The problem was the price: investors had paid in advance for decades of success.


Today’s AI buildout has important differences, and we could still be in the early-to-mid innings. Rising usage and new applications could create enough demand to justify much of today’s investment. And the largest infrastructure investors—Microsoft, Amazon, Alphabet, and Meta (the “hyperscalers”)—are among the most profitable businesses in the world, with robust balance sheets. 


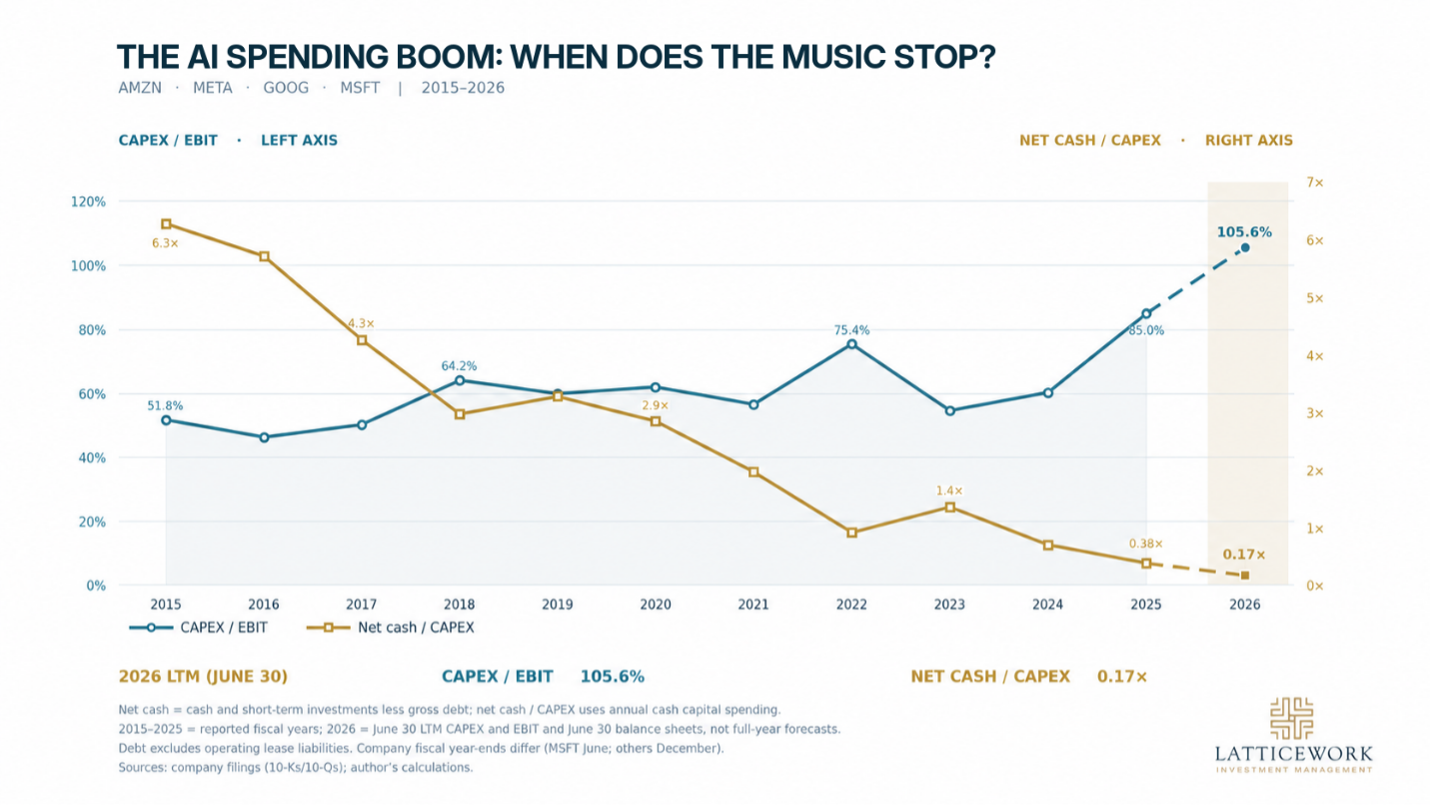
Industry spending is also remarkably concentrated: the four hyperscalers alone plan to spend more than $700 billion on capital projects in 2026 (based on April 2026 guidance),9 much of it on AI, and have largely funded the buildout with cash on hand and from operations. But that cushion is thinning.


As the chart below shows, the four companies’ combined capital expenditures have risen from about half of operating income (EBIT) in 2015 to 106% for the twelve months ended June 2026. Meanwhile, their net cash fell from roughly 6.3 times annual capital spending in 2015 to 0.17 times—roughly two months’ worth. They can still borrow or issue shares, and increasingly are,10 but the numbers suggest today’s pace of spending may be difficult to sustain.

And if these financially sound companies become more disciplined with spending, what happens to the businesses throughout the AI infrastructure supply chain that depend on continued investment? Some infrastructure operators have borrowed heavily to finance expansion,11 leaving them vulnerable if spending slows or access to capital weakens. Even a modest pullback by the hyperscalers could have a disproportionate impact on the industry.


Skepticism and optimism aren’t mutually exclusive. One can be wildly optimistic about the technology yet remain skeptical about the investment prospects.


Specifically, we question:


  1. Whether today’s supply-demand imbalance will persist years from now as new capacity comes online.
  2. How demand will change once compute is priced to allow infrastructure providers to earn an adequate return.
  3. Whether current rates of infrastructure spending can be sustained.
  4. Whether today’s valuations leave room for attractive returns for investors.


Investing is an art that requires balancing aggressiveness with conservatism, humility with confidence, and patience with gumption. When it comes to investing in AI, we think caution is warranted.


For us, caution means valuation discipline: we’re wary of owning businesses whose prices already assume years—or decades—of uninterrupted growth. As Cisco showed, a great company and a great investment aren’t always the same thing.


SOURCES

  1. Goldman Sachs, “Global AI Investment Is Forecast to Exceed $1 Trillion in 2026,” August 7, 2026. goldmansachs.com
  2. New York Times News Service, “Economy’s slump idles 95% of fiber-optic lines,” Deseret News, June 18, 2001. deseret.com
  3. U.S. railroad mileage, 1880 (93,267) and 1890 (163,597), per John F. Stover; American-Rails.com, “Railroads in the 1880s.” american-rails.com
  4. “Panic of 1893,” Wikipedia, citing W. N. Leonard, “The Decline of Railroad Consolidation,” Journal of Economic History, 1949. wikipedia.org
  5. Steven Klepper, “The Evolution of the U.S. Automobile Industry and Detroit as Its Capital,” Carnegie Mellon University, 2001. zew.de
  6. Argus Media, “Shale industry write-downs may top $300bn: Deloitte,” June 22, 2020 (shale industry: $300 billion cumulative negative free cash flow and more than 190 bankruptcies since 2010). argusmedia.com
  7. DrPeering.net (William B. Norton), “Internet Transit Pricing: Historical and Projected,” 2010 (U.S. internet transit prices per Mbps, 1998–2007). drpeering.net
  8. Cisco: revenue, Cisco Systems Form 10-K for fiscal 1999; market value, NPR, “Cisco Soaring,” March 28, 2000; valuation, AJ Bell, “Is 2025 more bubbly than 1999?”; price history, Sherwood News, “After a quarter century, Cisco surpasses dot-com bubble closing high,” December 11, 2025. sec.gov · npr.org · ajbell.co.uk · sherwood.news
  9. Sherwood News, “Alphabet, Amazon, Microsoft, and Meta plan more than $700 billion on capex this year,” April 30, 2026. sherwood.news
  10. International Monetary Fund, Global Financial Stability Report, October 2026, Background Analysis 1.1, “Rising Leverage in the AI Ecosystem.” imf.org
  11. The Next Web, “IMF warns $1.4tn in circular AI deals could deepen a market correction,” October 2026 (on the IMF’s October 2026 Global Financial Stability Report). thenextweb.com


IMPORTANT DISCLOSURES

Latticework Investment Management (“Latticework”) is an investment adviser registered with the State of Kansas. Registration does not imply a certain level of skill or training. More information about Latticework, including our Form ADV Part 2A brochure, is available upon request or at adviserinfo.sec.gov.


This commentary is provided for informational and educational purposes only and reflects Latticework’s views as of the date of publication, which are subject to change without notice. It is not intended as, and should not be construed as, investment, tax, legal, or accounting advice, or as an offer or solicitation to buy or sell any security. Please consult your own advisors before making any investment decision.

References to specific companies, including Nvidia, Cisco, Microsoft, Amazon, Alphabet, Meta, and Netflix,[C1]  are for illustrative purposes only and do not constitute a recommendation to buy, sell, or hold any security. Latticework and its clients may hold positions in securities mentioned.


Certain information is obtained from third-party sources believed to be reliable, but Latticework has not independently verified it and makes no representation as to its accuracy or completeness. The chart reflects Latticework’s calculations based on company filings. Forecasts and estimates, including those attributed to third parties, are inherently uncertain and may not be realized. Links to third-party websites are provided for convenience; Latticework is not responsible for their content.


Past performance is not indicative of future results. All investing involves risk, including the possible loss of principal.

Recent Posts

By Gus Konz • October 2, 2026
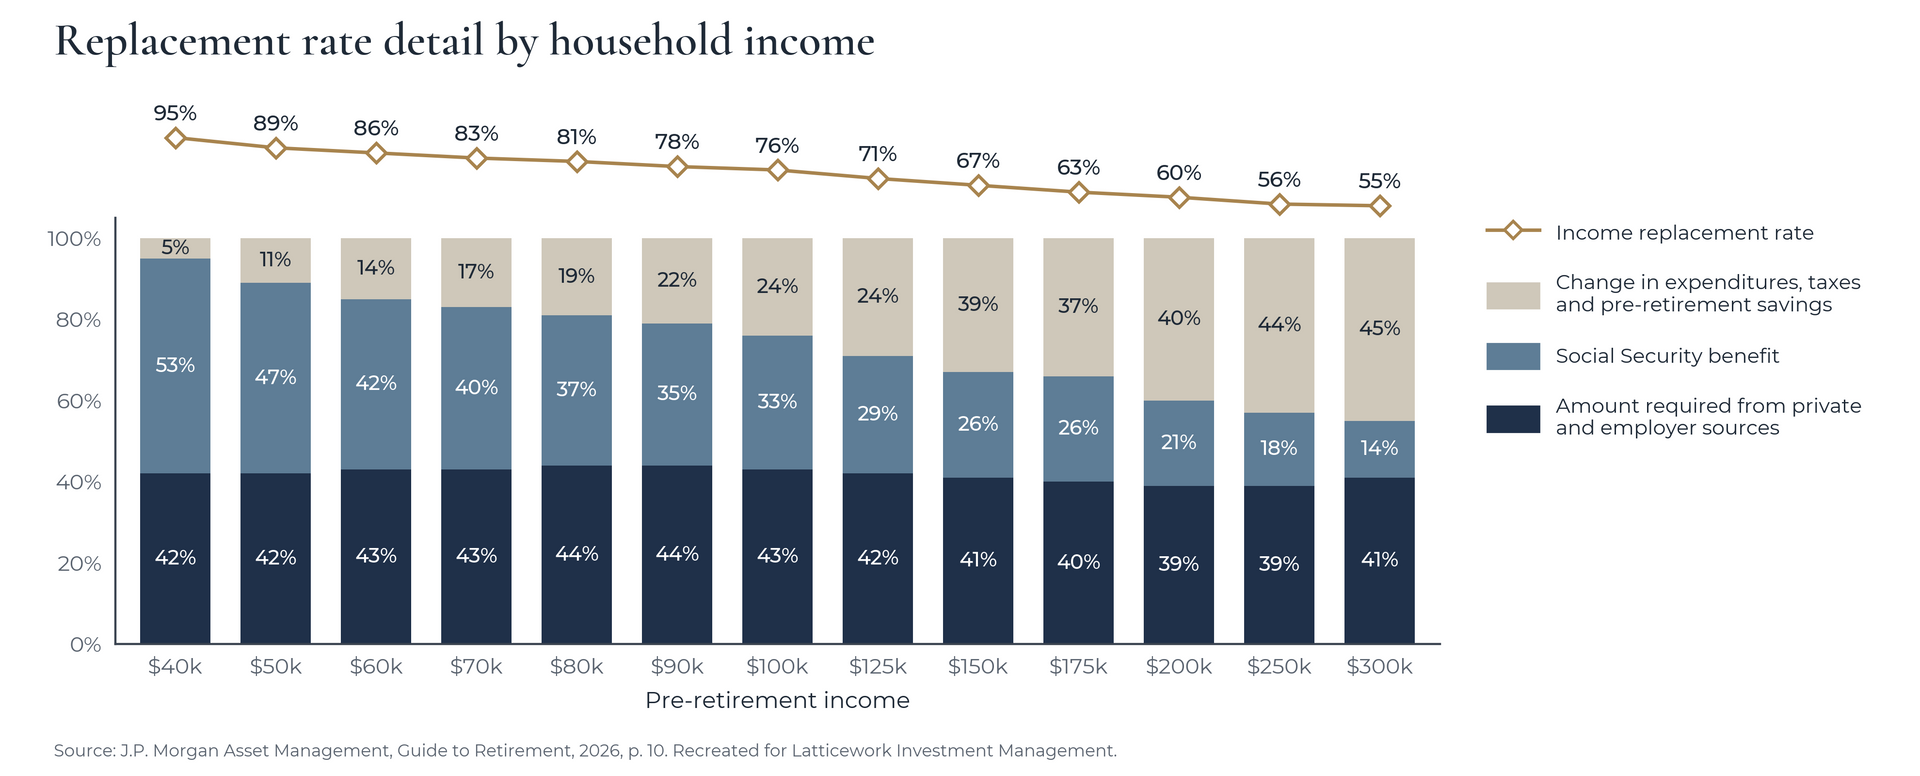
Whether you are in your 20s just starting out or ready to call it quits for good, everyone wants to know how much they need to retire, if they are on track, and how much they can expect to live on while in retirement. No matter your life stage, this infographic from J.P. Morgan is one of my favorite visual examples for understanding where you stand. 
By Gus Konz • September 29, 2026
October means open enrollment time for both Medicare and under-65 health insurance. The choices you make this fall lock in your costs for all of 2027, and several rules and numbers have changed. Here is what you need to know: Medicare Annual Enrollment runs October 15 through December 7. Anyone on Medicare can shop for their Medicare Part D drug plan or Medicare Advantage plan during this window. Changes take effect January 1. Review your Part D plan every year, even if you are happy with it. Plans change their premiums, covered drug lists, and preferred pharmacies every year. The plan that was cheapest for your prescriptions last year may not be this year. Enter your current prescriptions into the Plan Finder at Medicare.gov, or let us run the comparison with you. Part D cost-sharing limits are increasing in 2027. The maximum deductible rises to $700 (from $615 in 2026), and the annual out-of-pocket cap rises to $2,400 (from $2,100). Once you reach the cap, covered drugs cost $0 for the rest of the year. Already in a Medicare Advantage plan? You get one more chance to change. Between January 1 and March 31, people enrolled in a Medicare Advantage plan can make one change: switch to a different Advantage plan, or return to Original Medicare and add a Part D plan. This window cannot be used to move from Original Medicare into Advantage or to switch stand-alone Part D plans. Keep in mind that returning to Original Medicare does not guarantee you can buy a Medicare supplement, which may require medical underwriting. Medicare supplements, often called Medigap plans, can be shopped at any time, but usually require medical underwriting. Outside of your initial enrollment window, the insurance company can decline you or charge more based on your health, and the Annual Enrollment period does not change that. If you are healthy and your supplement premium keeps climbing, it may be worth pricing the same plan with other companies while you can still qualify. Missouri residents have an extra option. Missouri’s anniversary rule lets you switch to the same Medigap plan (for example, Plan G to Plan G) with any company, with no health questions, if you act within 30 days of your policy’s anniversary date. Kansas does not currently have a similar rule. IRMAA: watch your income from two years ago. Higher-income Medicare beneficiaries pay a surcharge on Part B and Part D premiums called IRMAA. It is based on your tax return from two years earlier, so your 2027 premiums are based on your 2025 income, and the income you create this year will set your 2028 premiums. In 2026, surcharges began at modified adjusted gross income above $109,000 for single filers and $218,000 for joint filers. The 2027 thresholds and Part B premium will be announced later this fall. IRMAA works like a cliff: going $1 over a threshold triggers the full surcharge for that bracket. Roth conversions, large IRA withdrawals, capital gains, and the sale of a business or property are the usual culprits. If your income has dropped because of certain qualifying life-changing events, such as retirement, reduced work, the death of a spouse, or divorce, you may be able to ask Social Security to use more recent income information by filing Form SSA-44. Under 65: The Health Insurance Marketplace Open enrollment begins November 1, 2026 on HealthCare.gov, which both Kansas and Missouri use. As of September 2026, HealthCare.gov lists January 15, 2027 as the final enrollment deadline. December 15 is the date that matters most. Choose your plan by December 15 for coverage that starts January 1. Plans chosen after that start February 1, which can leave a gap in coverage. Do not let your plan simply auto-renew. Premiums are rising again for 2027, several insurers are leaving markets or shrinking, and your plan’s doctors and hospitals may change. If your plan is discontinued, you could be moved into a replacement you did not choose. Log in, update your income estimate, and compare. Income limits for tax credits are back. The enhanced subsidies in place from 2021 through 2025 expired at the end of 2025 and have not been renewed. For 2027 coverage, premium tax credits are available only to households with income between 100% and 400% of the federal poverty level. Above 400% of the federal poverty level, the premium tax credit is generally unavailable, so even a small amount of income above the limit can result in the loss of a substantial premium tax credit.
By Gus Konz • September 22, 2026
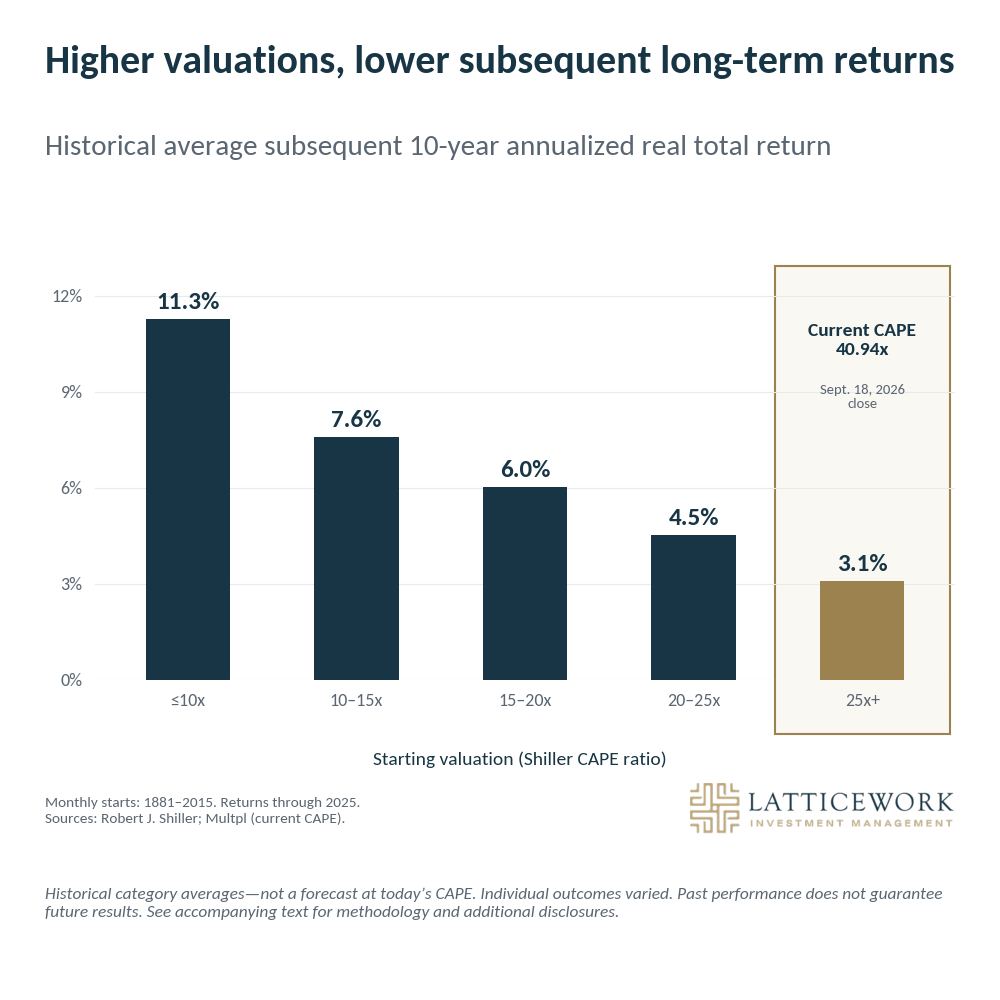
Something that Preston and I have discussed at length is our concern about current valuations across the stock market. Our greatest concern is high-priced U.S. growth stocks, though it is not confined to them. We are not alone in this. In a July 15, 2026, CNBC interview, Warren Buffett summed up the environment in ten words: “It’s tough to find values when everybody is preferring gambling.”[1] The ratio of total U.S. stock market capitalization to GDP — a measure Buffett himself popularized — now stands above 230%, within a few points of its all-time high.[2] In 2001, Buffett wrote that investors were playing with fire if that ratio approached 200%.[3] A different valuation measure tells a similar story: the Shiller CAPE ratio for the S&P 500 is approximately 41, a level reached only near the peak of the dot-com bubble.[4] Berkshire Hathaway's actions back up Buffett's words. After fourteen straight quarters as a net seller of stocks, the company ended March holding nearly $400 billion in cash — one of the largest corporate cash positions in American history.[5] I want to be careful here, because we are not calling for a market correction, and we view timing the market as a loser’s game. Buffett is not calling for one either (Berkshire turned net buyer of stocks in the second quarter of 2026). [5] High valuations are not a sell signal. They can persist for years, and waiting for a cheaper entry point can mean missing further gains. What elevated valuations do tell us is something more modest and more useful: the price you pay can influence the return you can reasonably expect. In our view, today’s prices leave very little cushion for disappointment. Most businesses growing at a normal rate are already priced as exceptional ones.
Preston Werth and Gus Konz
By Gus Konz • September 16, 2026
Planning for what we hope is a multi-decade retirement is something that deserves significant time and consideration. Here is where to start: Social Security Have a tailored Social Security plan for your retirement. An NBER study found that the median household headed by someone ages 45 to 62 gives up $182,370 in lifetime spending by not optimizing when they claim. For our clients, we use an analysis tool that requires your specific information and generates a plan tailored to you. Health Insurance Understanding the ins and outs of Medicare is vital. You need to consider all costs, not just the premiums, and ensure that you navigate the enrollment windows. Getting this wrong could lead to either unnecessary premiums or to lifelong penalties. However, retirement doesn’t always need to wait until Medicare starts. With some good financial planning and healthcare tax credits, an early retirement could be available. Investments Understand what you own and why. In most cases, we see that a moderate allocation between stocks and bonds is appropriate for pre-retirees and retirees. Which stocks and bonds you own is important. Ensure you have an advisor that can adequately explain the different types and which environments they make sense in. In the current environment we see a lot of growth-focused stock portfolios. Understand the risk inherent in growth stocks and consider value stocks, small-cap stocks, and international stocks too. Fees and Taxes These can erode your hard-earned wealth. Understand what your advisor costs, what the underlying securities cost, and if they are tax efficient. Financial products are not free. Annuities have fees, spreads, and commissions. Index funds have inefficiencies and expense ratios. Mutual funds can have 12b-1 fees and capital gains distributions. None of these are necessarily bad, but taxes and fees directly affect outcomes. Source: NBER Working Paper 30675 (2022) — https://doi.org/10.3386/w30675 Advisory services offered by Latticework Investment Management, LLC. The information above is for educational and informational purposes only and should not be considered personalized financial, investment, tax, or legal advice.