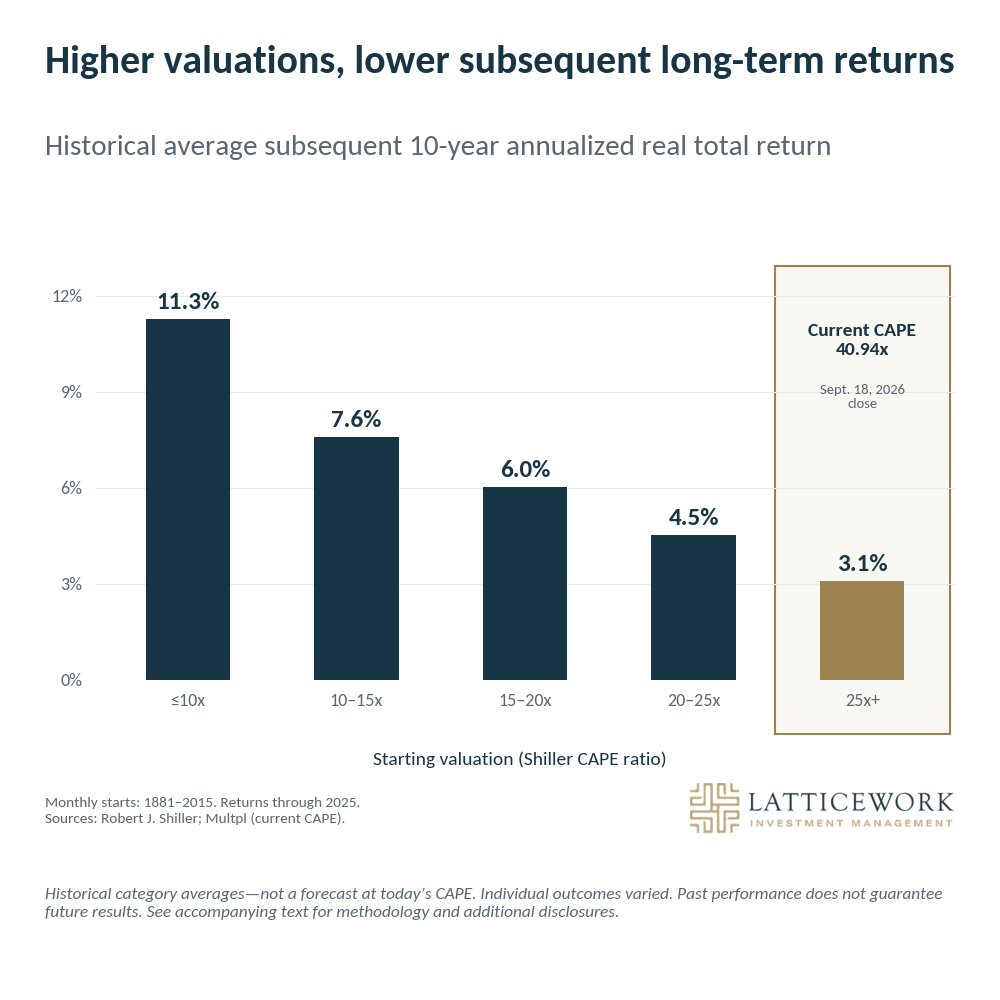
Something that Preston and I have discussed at length is our concern about current valuations across the stock market. Our greatest concern is high-priced U.S. growth stocks, though it is not confined to them. We are not alone in this. In a July 15, 2026, CNBC interview, Warren Buffett summed up the environment in ten words: “It’s tough to find values when everybody is preferring gambling.”[1] The ratio of total U.S. stock market capitalization to GDP — a measure Buffett himself popularized — now stands above 230%, within a few points of its all-time high.[2] In 2001, Buffett wrote that investors were playing with fire if that ratio approached 200%.[3] A different valuation measure tells a similar story: the Shiller CAPE ratio for the S&P 500 is approximately 41, a level reached only near the peak of the dot-com bubble.[4] Berkshire Hathaway's actions back up Buffett's words. After fourteen straight quarters as a net seller of stocks, the company ended March holding nearly $400 billion in cash — one of the largest corporate cash positions in American history.[5] I want to be careful here, because we are not calling for a market correction, and we view timing the market as a loser’s game. Buffett is not calling for one either (Berkshire turned net buyer of stocks in the second quarter of 2026). [5] High valuations are not a sell signal. They can persist for years, and waiting for a cheaper entry point can mean missing further gains. What elevated valuations do tell us is something more modest and more useful: the price you pay can influence the return you can reasonably expect. In our view, today’s prices leave very little cushion for disappointment. Most businesses growing at a normal rate are already priced as exceptional ones.
Planning for what we hope is a multi-decade retirement is something that deserves significant time and consideration. Here is where to start: Social Security Have a tailored Social Security plan for your retirement. An NBER study found that the median household headed by someone ages 45 to 62 gives up $182,370 in lifetime spending by not optimizing when they claim. For our clients, we use an analysis tool that requires your specific information and generates a plan tailored to you. Health Insurance Understanding the ins and outs of Medicare is vital. You need to consider all costs, not just the premiums, and ensure that you navigate the enrollment windows. Getting this wrong could lead to either unnecessary premiums or to lifelong penalties. However, retirement doesn’t always need to wait until Medicare starts. With some good financial planning and healthcare tax credits, an early retirement could be available. Investments Understand what you own and why. In most cases, we see that a moderate allocation between stocks and bonds is appropriate for pre-retirees and retirees. Which stocks and bonds you own is important. Ensure you have an advisor that can adequately explain the different types and which environments they make sense in. In the current environment we see a lot of growth-focused stock portfolios. Understand the risk inherent in growth stocks and consider value stocks, small-cap stocks, and international stocks too. Fees and Taxes These can erode your hard-earned wealth. Understand what your advisor costs, what the underlying securities cost, and if they are tax efficient. Financial products are not free. Annuities have fees, spreads, and commissions. Index funds have inefficiencies and expense ratios. Mutual funds can have 12b-1 fees and capital gains distributions. None of these are necessarily bad, but taxes and fees directly affect outcomes. Source: NBER Working Paper 30675 (2022) — https://doi.org/10.3386/w30675 Advisory services offered by Latticework Investment Management, LLC. The information above is for educational and informational purposes only and should not be considered personalized financial, investment, tax, or legal advice.